CPV Signs $825 Million Refinancing for PJM Gas Plants Shore, Maryland
OPC Energy's CPV unit entered the non-recourse deal on Oct. 27 for its 725 MW Shore and 745 MW Maryland plants, cutting the loan spread to SOFR plus 2.5% and paying CPV about $130 million at closing.
2 min readAI-assisted
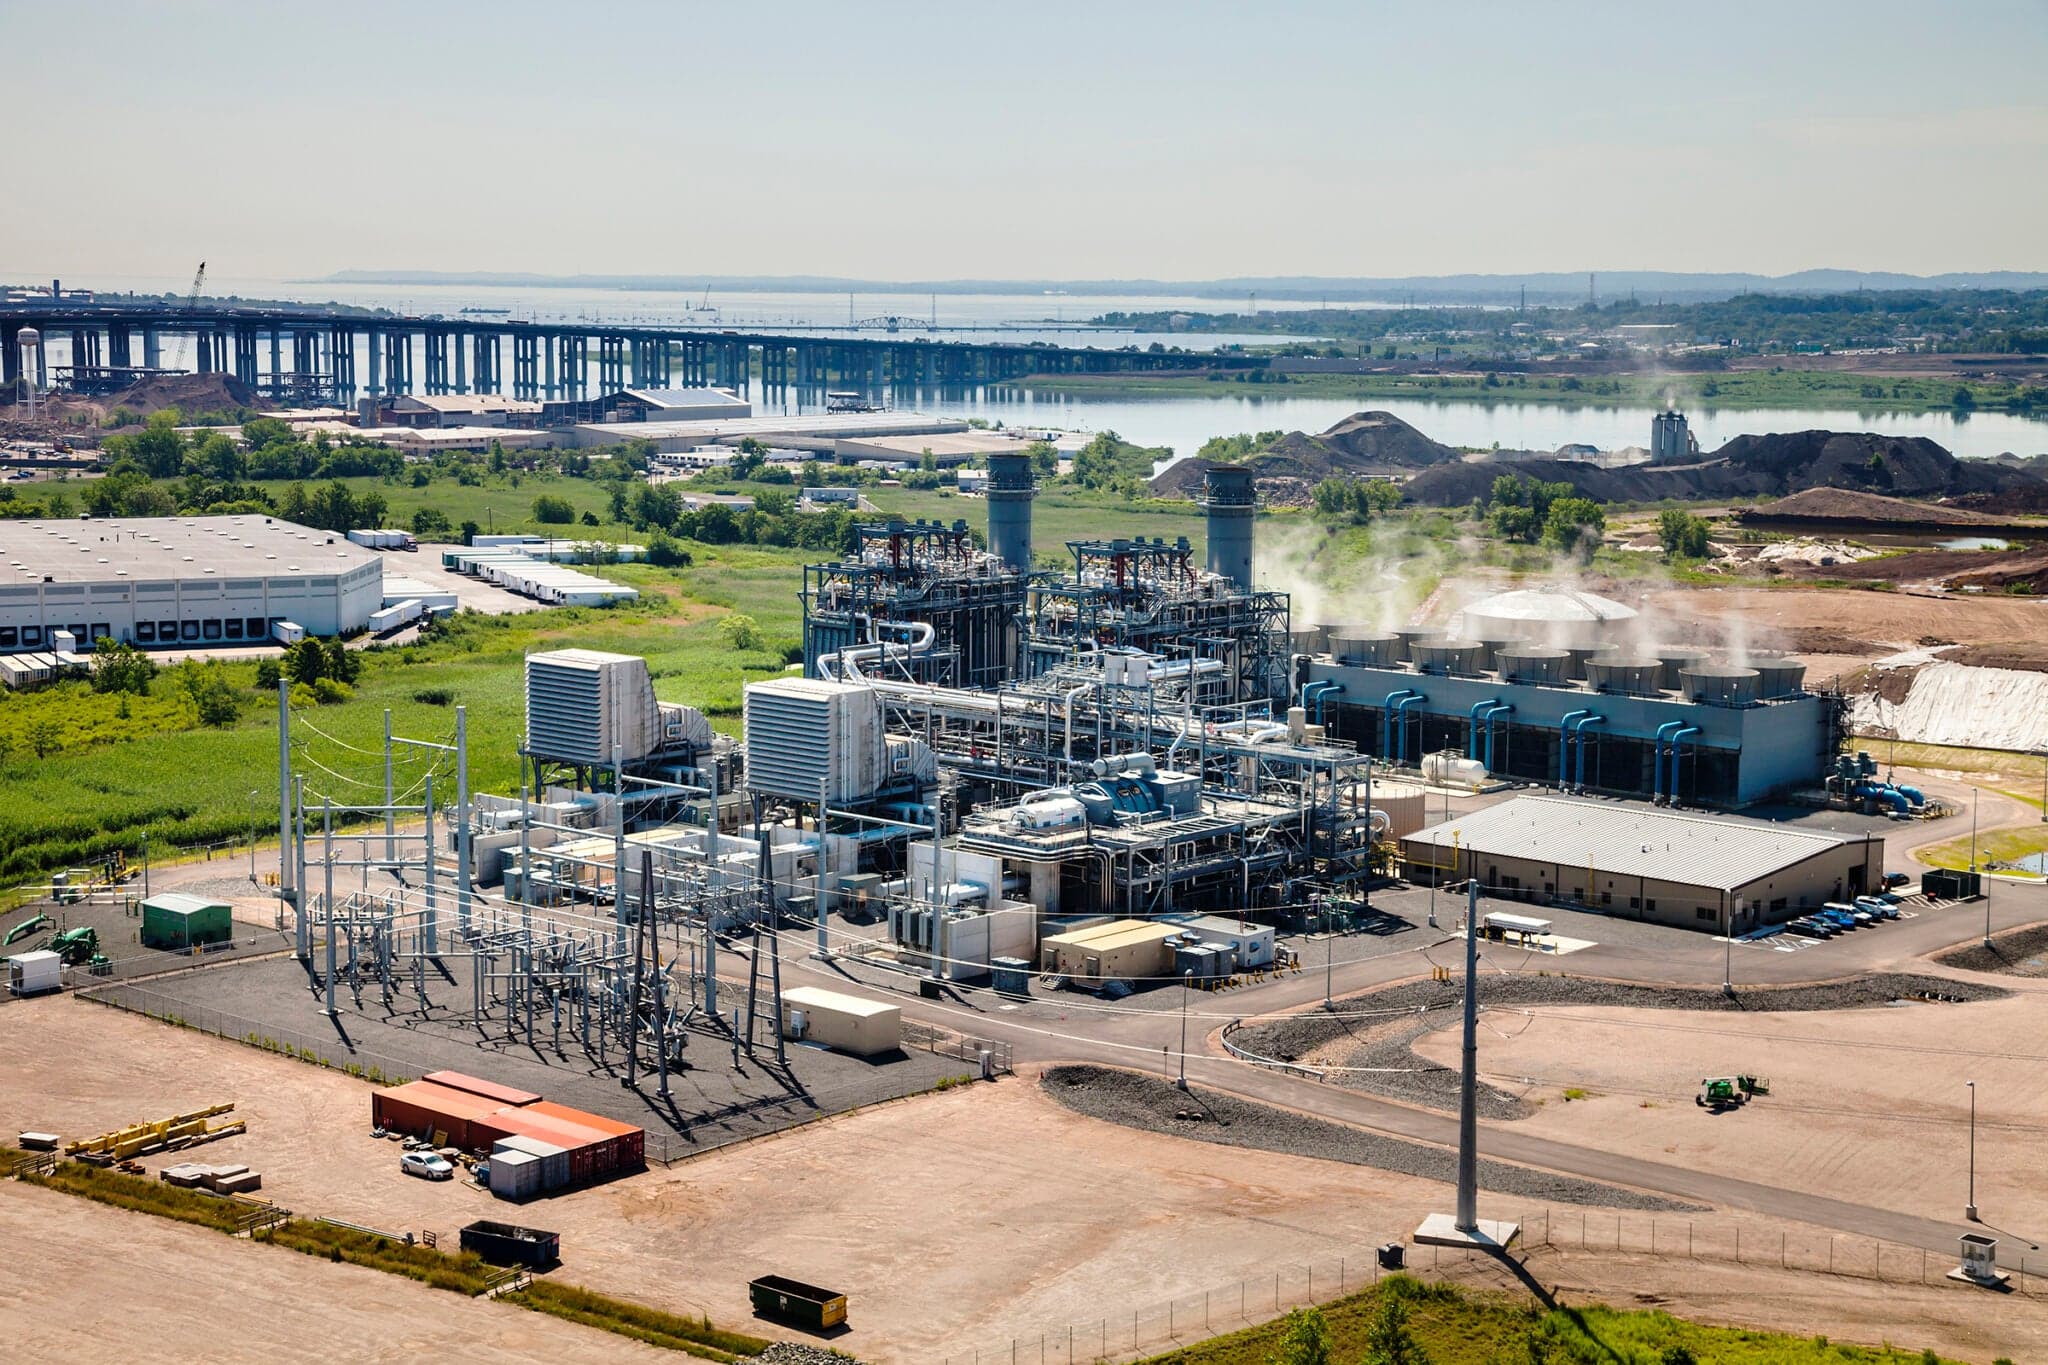
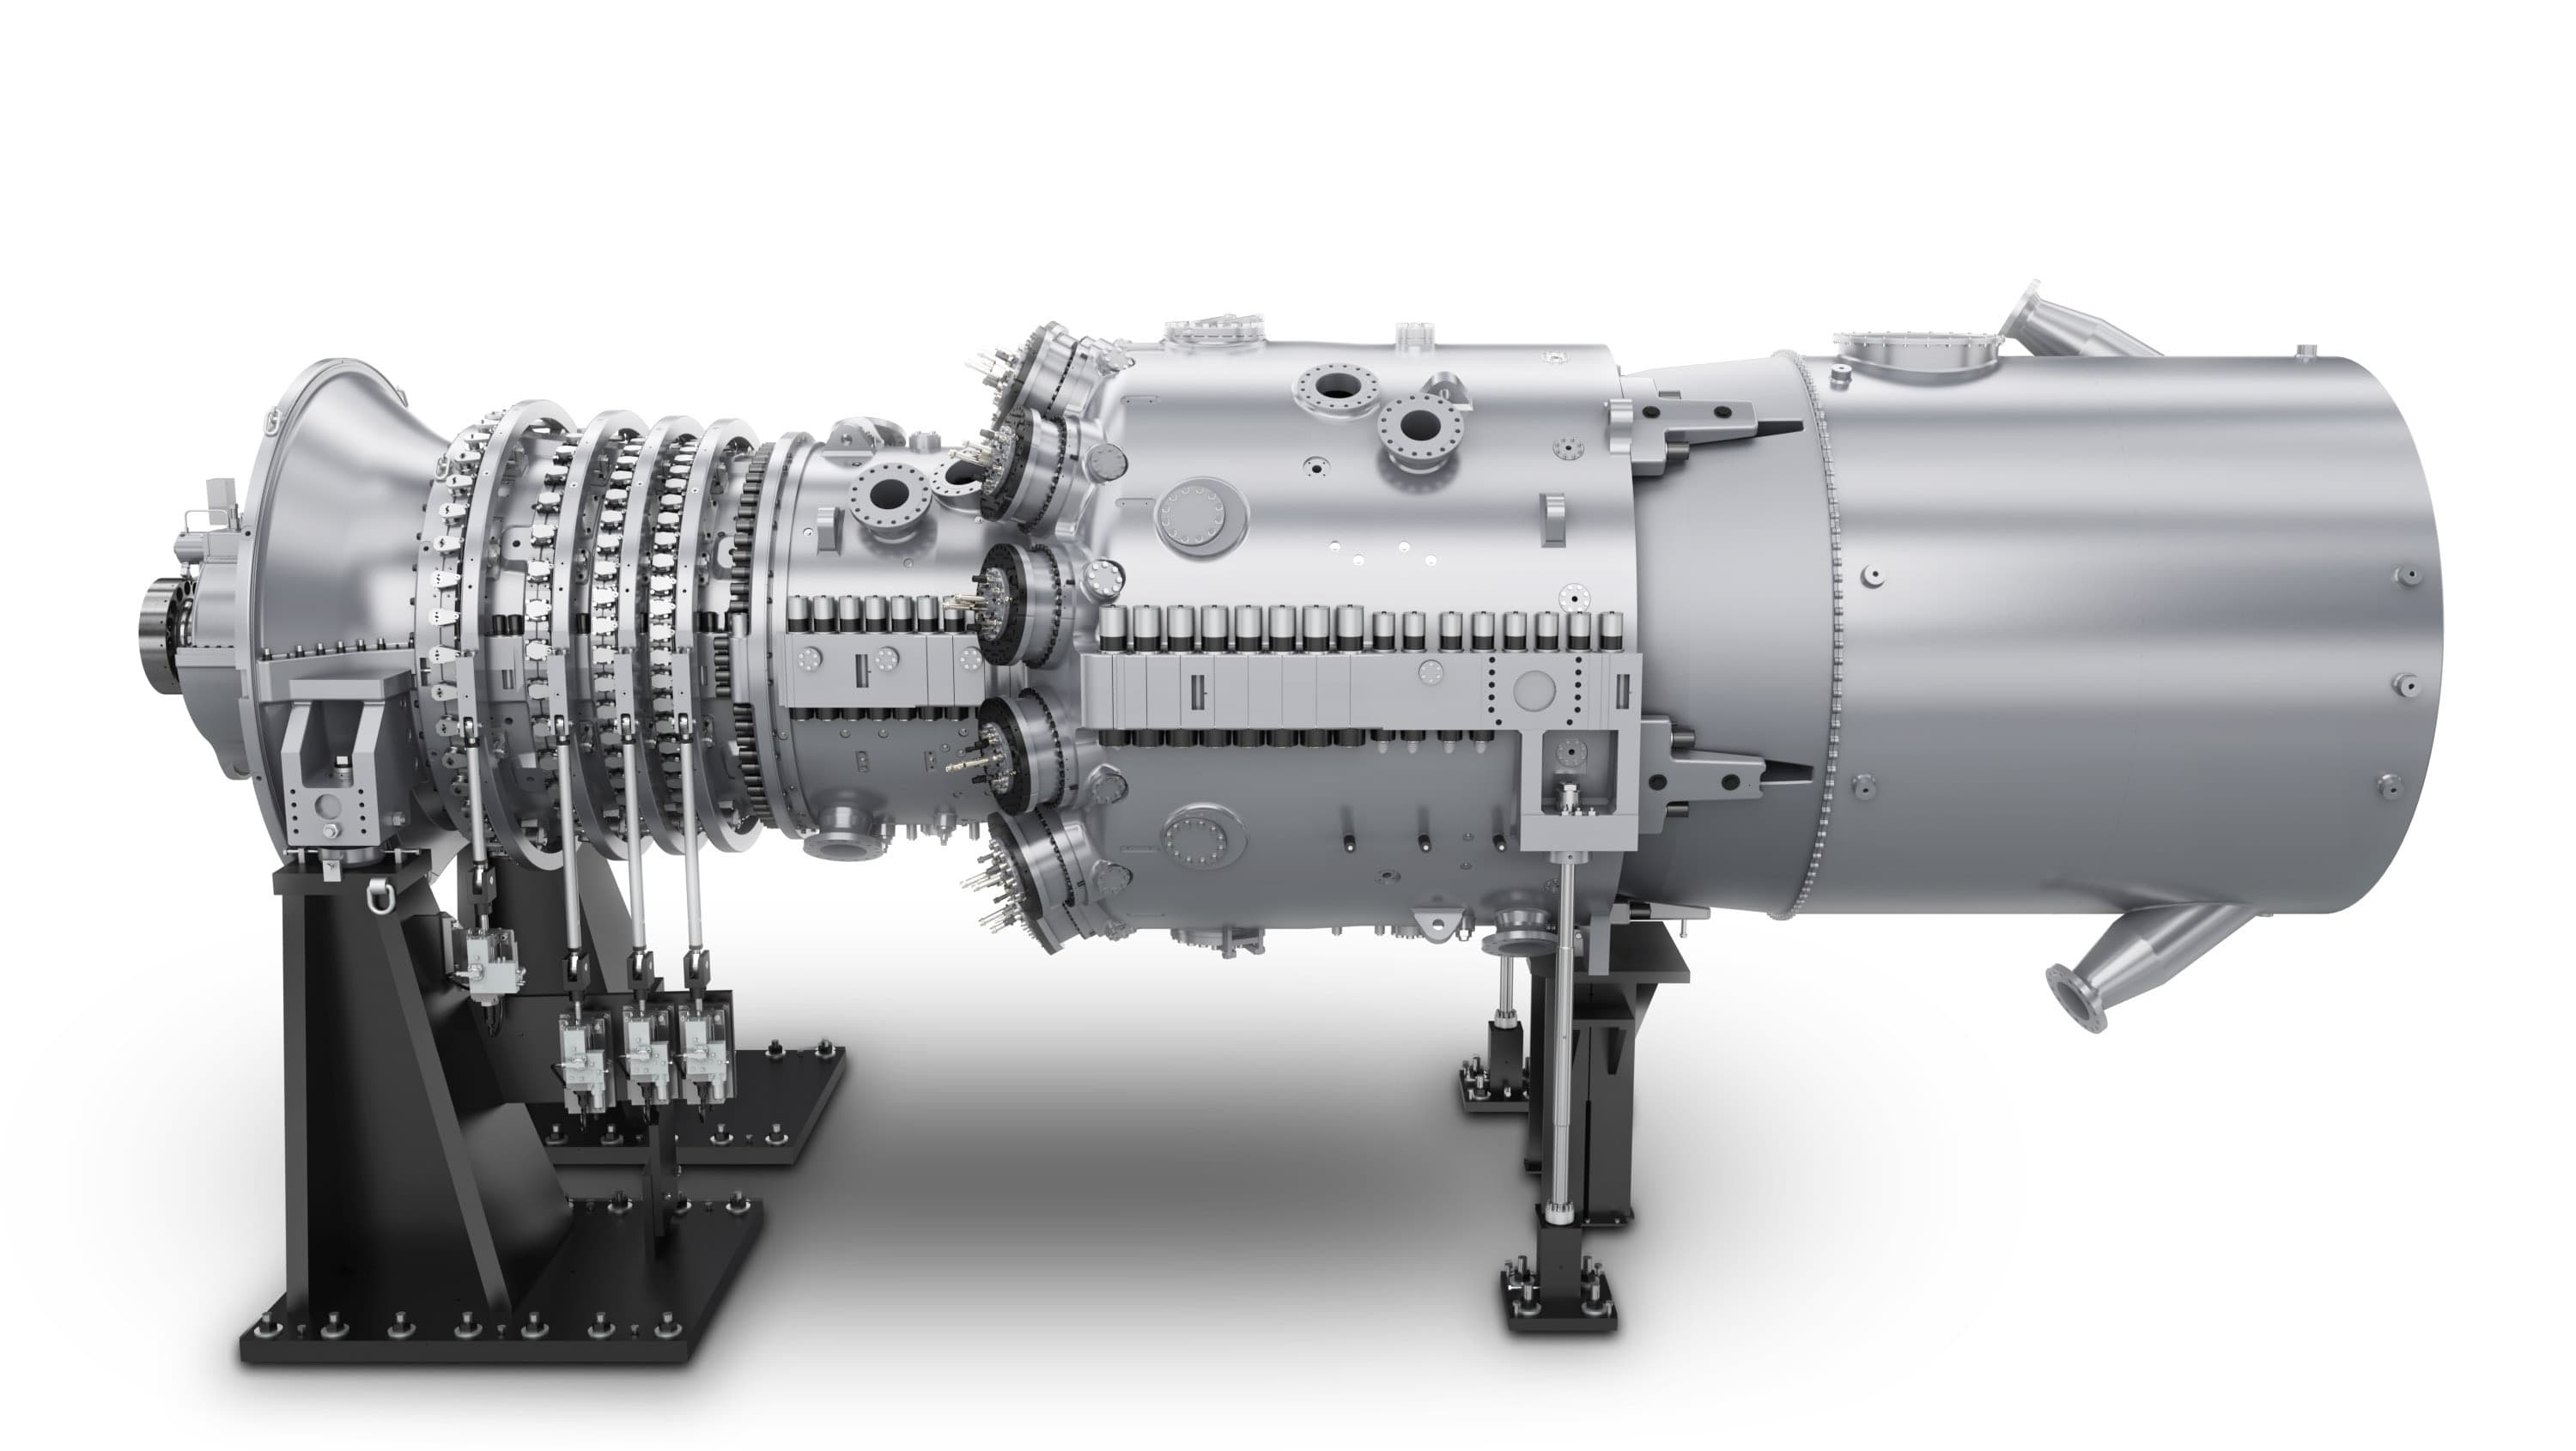
CPV's Woodbridge Energy Center in New Jersey, listed at 725 MW. The photo shows one of the two plants in the financing.
Image: CPV
Source · Press image from the CPV website, used for news reporting.
CPV Generation Holdings, LLC entered into an $825 million financing agreement with a syndicate of lenders on Oct. 27 for its Shore and Maryland gas-fired power plants, OPC Energy said in a release on Oct. 29. Kenon Holdings, OPC's parent, disclosed the deal in a Form 6-K filed with the U.S. Securities and Exchange Commission on Oct. 28.
Shore and Maryland are natural gas-fired combined-cycle plants in the PJM electricity market, with capacities of 725 MW and 745 MW, according to OPC. CPV lists them on its website as the Woodbridge Energy Center in Woodbridge Township, New Jersey, running since January 2016, and the St. Charles Energy Center in Waldorf, Maryland, running since February 2017. The borrower is a wholly owned indirect subsidiary of CPV Group LP, which OPC owns 71%, the filing says.
The deal folds the two plants' separate project financings into one facility. Most of the money repays existing project debt, and about $130 million goes to CPV as a dividend at closing, according to both the filing and the release. OPC says the package also supports the plants' working capital and collateral needs.
Terms: SOFR Plus 2.5% on a Seven-Year Loan
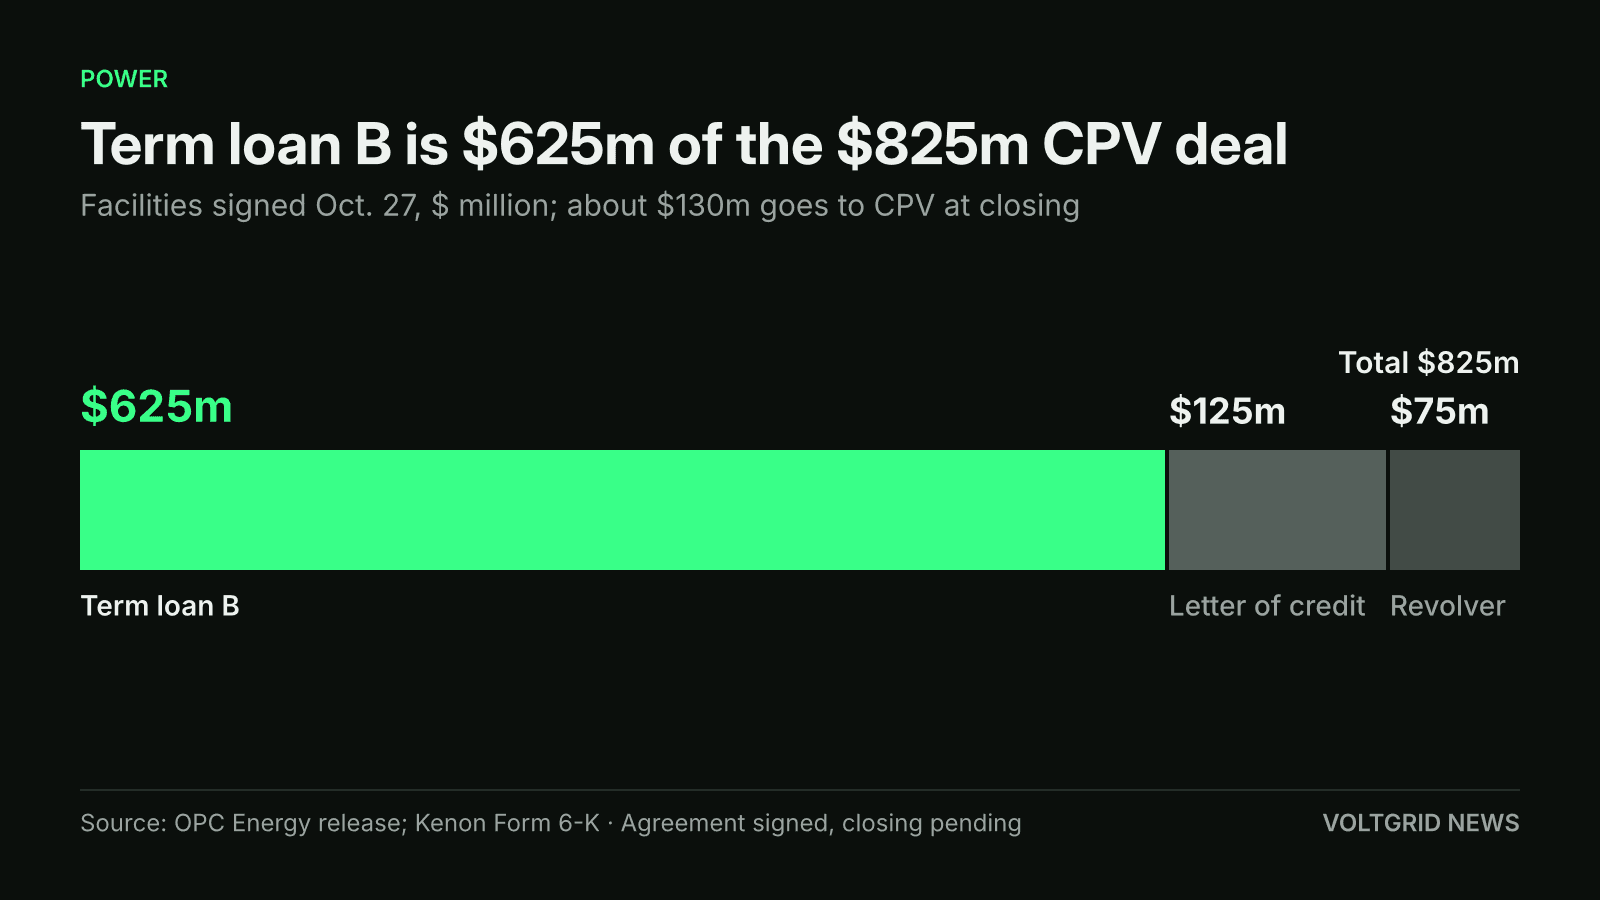
The term loan B makes up $625 million of the $825 million financing, which is signed but not yet closed.
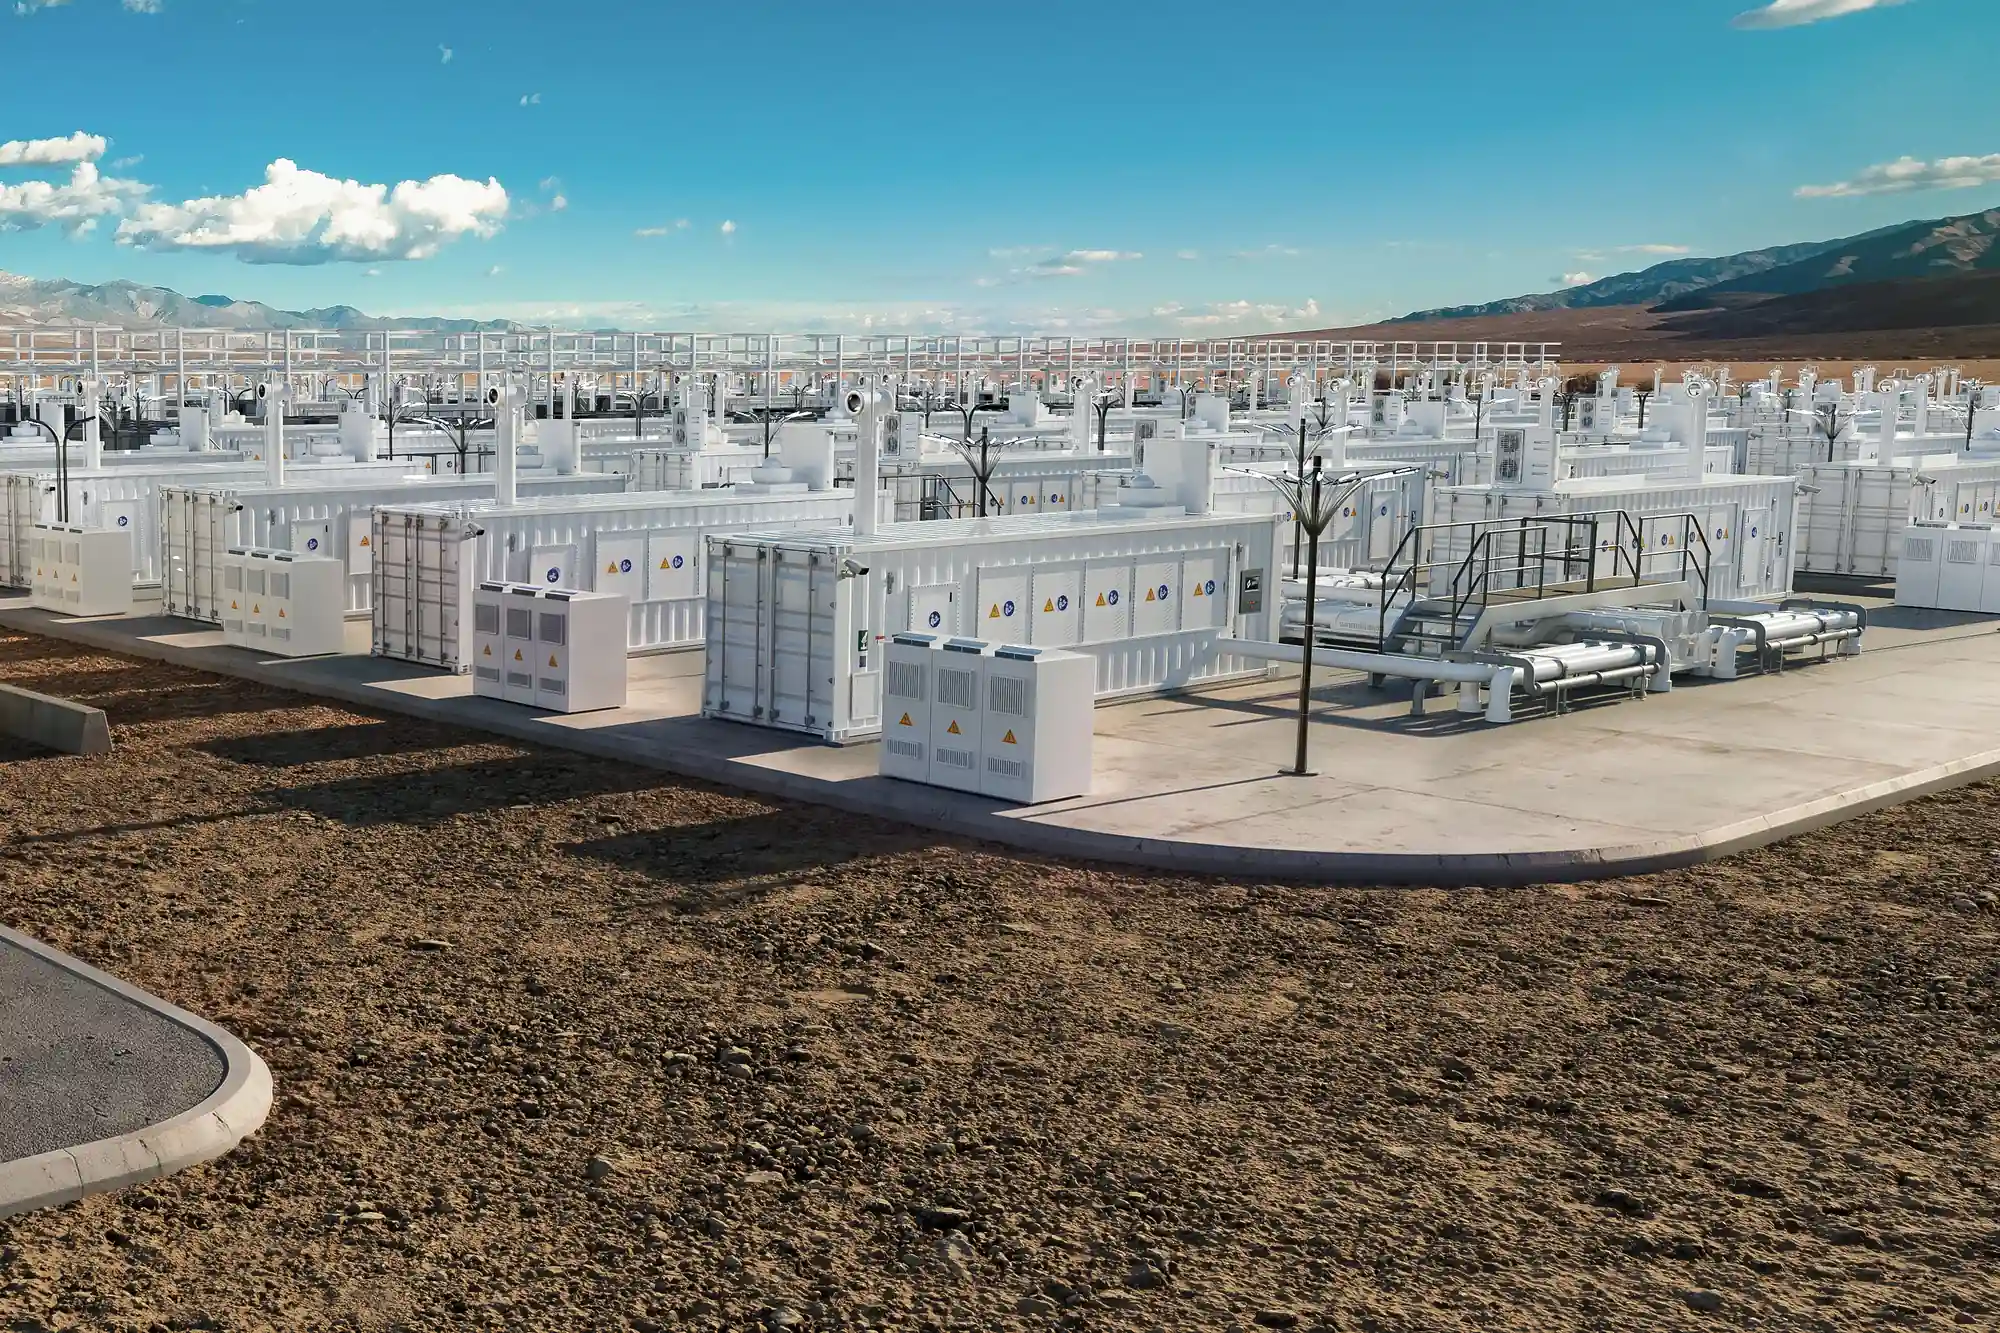
Illustration (AI-generated)
The $825 million is split three ways: a $625 million term loan B, a $125 million letter of credit facility and a $75 million revolving credit facility. OPC says the term loan B pays SOFR plus 2.5%, matures in seven years and has no scheduled amortization. SOFR is the Secured Overnight Financing Rate, a benchmark for dollar loans. The revolver pays SOFR plus 2.25%, and the letter of credit facility carries a fixed issuance rate of 2.25%. Both run for five years, the company said.
OPC calls the term loan spread a 75-basis-point cut from the previous 3.25%. It did not say which earlier loan carried that rate. A Kenon filing from February 2025 put the Shore plant's previous term loan B at SOFR plus 3.75%, on $325 million due 2032.
Lenders can force early repayment through a cash sweep tied to leverage that ranges from 0% to 50%, OPC said. It added that both plants currently sit at the lower end of that range.
How a Non-Recourse Plant Refinancing Works
The financing is non-recourse to CPV, the filing says, so the debt is repaid from the two plants rather than from the parent. It is secured by a first-ranking pledge on each plant and its assets plus a pledge over the equity interests in the borrower. The agreement includes customary financial covenants and a negative pledge, and it limits new debt, asset sales and distributions.
For readers tracking power supply for AI data centers, the deal adds no new capacity: both plants already operate, and neither the filing nor the release ties them to a data center customer. It does show what lenders now charge to refinance two existing combined-cycle plants in PJM. Voltgrid News has covered other gas-plant funding, including Alliant Energy's DOE loan for gas and storage in Iowa.
What Is Not Confirmed Yet
This is a signed agreement, not a closed deal. The filing says it is subject to conditions precedent to closing, and the dividend and the repayment of existing debt happen at closing. Kenon also cautions that the closing, the disbursement of the loans and the use of proceeds are subject to risks, including compliance with the agreement's covenants. Neither document names the lenders, a closing date or the plants' offtakers.